
Business-owner mortgages rarely need more hype. They need someone willing to understand the file.
A business owner can be financially successful and still have a mortgage application that looks complicated on paper.
- Salary
- Dividends
- Corporate income
- Variable earnings
- Rental properties
- Tax planning
- Multiple sources of income
Igor’s job is to understand how those pieces fit together, explain how a lender may view them, and help you make a more informed mortgage decision.
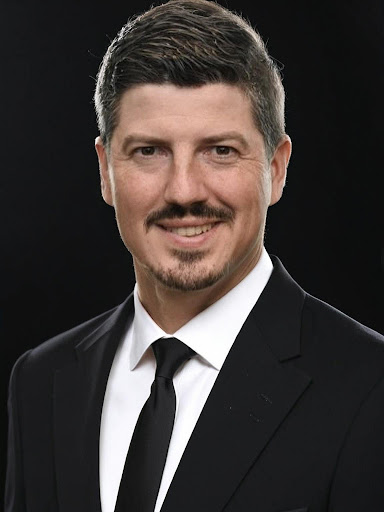
Igor Perett
Mortgage Agent Level 1 · FSRA Licence #M26000762
Affinity Mortgage Solutions Inc. · Brokerage #13093
Mortgage professional since 2010
Former Mortgage Specialist with Scotiabank, CIBC & RBC
Mortgage Agent Level 1
FSRA Licence #M26000762
Affinity Mortgage Solutions Inc.
Brokerage #13093
Experience with mortgages from more than one side of the industry.
Igor began working in mortgages in 2010. His career included Mortgage Specialist roles with:
- Scotiabank
- CIBC
- RBC
Working within major financial institutions provided first-hand experience with the processes, documentation and lending criteria involved in mortgage financing.
It also reinforced an important lesson:
One lender’s answer is not the entire mortgage market.
Different institutions can have different:
- Lending policies
- Documentation requirements
- Income approaches
- Risk appetites
- And mortgage products
Today, Igor works through Affinity Mortgage Solutions Inc., Dominion Lending Centres.
That gives him the ability, within his licence scope, to consider mortgage options beyond one institution when the circumstances call for it.
Because “What do you make?” is not always a one-line answer.
A salaried employee may be able to answer that question with a T4. A business owner might answer:
“It depends what you mean.”
- The company earns one amount.
- The owner pays themselves another.
- Part of the compensation may be salary. Part may be dividends.
- Some earnings may stay inside the company.
The accountant may appropriately focus on tax efficiency.
The mortgage lender needs to establish income it can verify and use.
Those moving parts are where preparation becomes valuable.
Igor’s focus is helping borrowers understand that gap before it becomes a surprise during the mortgage process.
Clarity before application.
Igor’s approach is intentionally straightforward.
- 1
Understand the goal
What are you trying to accomplish?
- Buy?
- Renew?
- Refinance?
- Invest?
- Recover from a previous decline?
- 2
Understand the financial picture
- How do you earn?
- What do you own?
- What do you owe?
- What documentation exists?
- What may require explanation?
- 3
Identify the important issues
- What looks strong?
- What may create a problem?
- What information is missing?
- 4
Explain the available direction
- Proceed?
- Prepare more documentation?
- Consider another suitable lender?
- Change part of the plan?
- Wait?
The objective is not to submit an application as quickly as possible.
It is to understand what the application needs before it is submitted.
You should know what is happening to your mortgage file.
When working with Igor, the goal is for you to understand:
What is being requested
You should know why a document or piece of information matters.
What the lender is considering
Mortgage decisions should not feel like messages disappearing into a black box.
What options are being discussed
Different routes can carry different costs and trade-offs.
What happens next
You should know the next step rather than constantly wondering where the file stands.
What has not been promised
A mortgage agent cannot guarantee lender approval.
Final underwriting and approval remain with the lender.
Not every file should be pushed forward today.
That may not create a mortgage transaction today.
It can still be the right answer for the borrower.
Igor’s role is to help you understand the options — not manufacture urgency where it does not belong.
There are circumstances where the better decision may be to:
- Improve part of the credit profile
- Build a longer income history
- Organize documentation
- Reduce debt
- Accumulate additional funds
- Wait for a mortgage to mature
- Or change part of the purchase plan
Igor Perett
Mortgage Agent Level 1
- Licence
- FSRA Licence #M26000762
- Experience
- Mortgage professional since 2010
- Previous Mortgage Specialist experience
- Scotiabank · CIBC · RBC
- Currently with
- Affinity Mortgage Solutions Inc.
Dominion Lending Centres
Mortgage Brokerage #13093
Independently owned and operated - Serving
- Clients across Ontario
In person wherever suits you, at the office, by phone or on Zoom - Languages
- English · Russian
Know who is handling your mortgage.
Igor is licensed in Ontario as a Mortgage Agent Level 1.
That licence sets which lenders Igor works with directly, and it is why every recommendation you get is one he is licensed to stand behind.
When a file calls for financing beyond that, such as a private mortgage, Igor has it covered through his partnerships with licensed Mortgage Agent Level 2 and broker partners. He connects you with the right partner, and the private mortgage is arranged through them, so you have a solution either way.
You can check it yourself: licence #M26000762 (Igor Perett) is on FSRA’s public register.
View Igor’s licence on FSRA’s registerSometimes your bank may be the right answer.
Working with a mortgage agent does not mean your existing financial institution is automatically wrong. The difference is perspective.
A bank representative
Works within that institution’s products and policies.
A mortgage agent in the broker channel
Can consider available options from multiple lenders within their access and licence scope.
Sometimes that leads somewhere different.
Sometimes it confirms that staying with your bank makes sense.
Either outcome can be useful.
Igor may be a particularly useful starting point if:
- You own an incorporated business
- You are self-employed
- You receive salary and dividends
- Your taxable income does not seem to reflect your business performance
- You earn significant commissions
- You own rental properties
- Your finances involve multiple income sources
- A bank has already declined you
- You are planning a purchase before you urgently need the mortgage
- Or you simply want someone to explain the decision clearly before you commit
Not every mortgage belongs here.
If your circumstances require expertise or licensing outside Igor’s scope, the right outcome may be a referral.
The goal is not to keep every transaction.
The goal is to get the borrower to the appropriate solution.
You do not need to know which mortgage you need before you call.
Tell Igor what you are trying to do, how you earn, and what concerns you about the mortgage.
Then work forward from there.
No credit check to start · Initial consultation at no cost · Nothing submitted without your approval