Mortgage solutions for business owners

Start with what you’re trying to accomplish — not with a mortgage product.

Buying a home, renewing a mortgage, refinancing or purchasing an investment property can all require different strategies.

For a business owner or self-employed borrower, there is another layer:

How will the lender assess your income?

Igor helps you understand the financial picture first, then determine which mortgage routes may fit the goal.

No credit check to start · Initial consultation at no cost · Nothing submitted to a lender without your approval

Since 2010

Mortgage professional

Former Scotiabank, CIBC & RBC Mortgage Specialist

FSRA Mortgage Agent Level 1

Licence #M26000762

Serving Ontario

In person, office, phone or Zoom

What are you trying to do?

Choose the situation that looks most like yours.

Buying a home

Know the financing before you fall in love with the property.

For a salaried employee, estimating buying power can be relatively straightforward.

For a business owner, the number may depend on much more than the salary appearing on a T4.

The goal is not to give you the biggest possible number.
It is to help you shop within a range you can defend when the lender actually reviews the file.

Before you start making offers, it helps to understand:

  • What income a lender may be prepared to use
  • How salary, dividends and business income may be treated
  • What documentation may be required
  • How your existing debts affect the application
  • And what price range can realistically be supported
Renewing your mortgage

A renewal notice is an offer — not an instruction.

When your mortgage approaches maturity, your existing lender may send you a renewal offer. It can be convenient to sign it and move on.

But a renewal is also an opportunity to review whether the mortgage still fits.

Your circumstances may have changed since the mortgage was originally arranged. Your business may have grown. Your income structure may have changed. You may have accumulated more equity. Your borrowing needs may be different.

Sometimes staying with the current lender is perfectly reasonable.
The point is to make that decision deliberately.

Before renewing, it can be useful to understand:

  • The terms being offered by your current lender
  • Whether other available options are worth considering
  • The costs and practical implications of switching
  • Whether your current mortgage structure still makes sense
  • And whether you want to make other changes at the same time

Refinancing

Your home equity is an asset. Using it should have a purpose.

A refinance can potentially change the amount, structure or terms of your mortgage.

But access to equity does not automatically make borrowing against it the right decision. A refinance can involve costs, qualification requirements and a change to your overall debt picture.
The useful question is not:“How much equity can I pull out?”It is:“What am I trying to accomplish, and does refinancing improve the situation?”
Igor can help you understand the available mortgage route, the numbers involved and the trade-offs before you decide.

Business owners may consider refinancing for many reasons:

  • Consolidating higher-cost debt
  • Accessing equity for renovations
  • Reorganizing personal cash flow
  • Financing another property
  • Making a major purchase
  • Or creating financial flexibility

Investment property

The mortgage should support the investment — not undermine it.

Financing an investment property introduces additional questions beyond the purchase price.

For business owners, the interaction between business income and existing real-estate obligations can make the file more complex.
The objective is to understand the financing before committing to the investment.

Depending on the property and lender, the review can involve:

  • Your personal and business income
  • Existing mortgage obligations
  • Rental income
  • Down payment and available funds
  • Property type
  • The number of properties already owned
  • And the overall strength of the application
One goal. Two questions.

For self-employed borrowers, every mortgage starts with two separate questions.

Question 1

Does the mortgage make sense?

That means looking at:

  • The payment
  • Interest cost
  • Mortgage structure
  • Available equity
  • Term
  • Flexibility
  • And the purpose of the financing

Question 2

Can the lender support the application?

That means looking at:

  • Income
  • Documentation
  • Credit
  • Existing obligations
  • Available funds
  • The property
  • And the lender’s criteria

Those are not the same question.

A mortgage can look perfectly reasonable financially and still be difficult to qualify for under one lender’s policies.

That is why Igor starts with the full picture before focusing on a particular mortgage product.

The first step

You do not need to choose the lender before speaking with Igor.

In fact, that is usually not the best place to start.

  1. Begin with:

    What do you want to accomplish?

  2. Then:

    How do you earn?

  3. Then:

    What does the financial picture support?

  4. And finally:

    Which available lending routes may fit?

That sequence helps separate the mortgage decision from the lender-selection decision.

During the initial review, Igor can help you understand:

  • What your goal requires
  • How your income may be viewed
  • What documentation may matter
  • Potential obstacles worth investigating
  • And what the logical next step may be
Rate is one part of the decision

A low rate does not make the wrong mortgage the right mortgage.

Rate matters. But it is not the only variable. Depending on the transaction, other considerations can include:

  • Mortgage term
  • Fixed versus variable structure
  • Prepayment options
  • Potential penalties
  • Portability
  • Lender restrictions
  • Refinancing flexibility
  • Fees
  • And qualification requirements

For a self-employed borrower, there is one more:

Will the lender accept the income structure?

That is why the process begins with fit rather than advertising the lowest number on the page.

The difference in one minute

Purchase vs. renewal vs. refinance.

Buying
How much property can reasonably be financed and which lending routes may fit
Renewing
Whether to keep the existing mortgage arrangement or consider available alternatives
Refinancing
Whether changing the existing mortgage helps accomplish another financial objective
Investment Property
Whether the financing supports both the purchase and the broader financial picture
Bank Decline
Why the original application failed and whether there is a reasonable next route
The process

Mortgage first principles: goal → numbers → file → lender.

Define the goal

What are you actually trying to accomplish?

  • A larger house?
  • A better mortgage structure?
  • Debt consolidation?
  • Another property?
  • Access to equity?

Understand the financial picture

How do you earn?

What do you own?

What do you owe?

What has changed?

Determine what may qualify

Review the income and documentation a lender may consider and identify potential issues before submission.

Consider available solutions

Compare relevant mortgage routes, costs and trade-offs.

Decide

You choose whether you want to proceed.

Nothing is submitted to a lender without your approval. Final approval always rests with the lender.

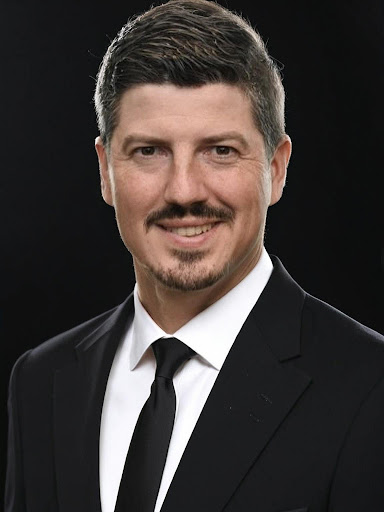
Igor Perett, Mortgage Agent Level 1

Igor Perett

Mortgage Agent Level 1 · Licence #M26000762

Experience matters more when the file isn’t standard

Igor has worked with mortgages from inside major banks and through the broker channel.

Igor Perett began his mortgage career in 2010.

Before becoming a mortgage agent in the broker channel, he worked as a Mortgage Specialist with Scotiabank, CIBC and RBC.

That experience provided exposure to mortgage lending from inside major financial institutions.

Today, Igor works with borrowers across Ontario through Affinity Mortgage Solutions Inc., Dominion Lending Centres.

His focus includes business owners and self-employed borrowers whose income can require more explanation than a conventional salaried application.

Mortgage Agent Level 1, Licence #M26000762

Affinity Mortgage Solutions Inc., Dominion Lending Centres, Brokerage #13093
Independently owned and operated

Serving clients across Ontario in person wherever suits you, at the office, by phone or on Zoom, in English and Russian.

Common questions

Frequently asked questions

No.

Start with the objective. Igor can help you understand which mortgage routes may be relevant after reviewing the circumstances.

Igor can help assess the information available and discuss what may be realistic based on lender criteria.

Any formal approval or commitment ultimately comes from the lender after reviewing the complete application and property.

No.

A credit check is not required for the initial conversation.

If reviewing credit becomes appropriate later, Igor will explain why before proceeding.

For a self-employed borrower, doing so can be useful.

Understanding how income may be assessed before shopping can reduce the risk of building a purchase around a financing assumption that later changes.

Potentially, but changing a mortgage before maturity can involve costs or penalties.

Those costs should be understood before deciding whether refinancing makes financial sense.

No.

Sometimes renewing with the existing lender makes sense. Sometimes it is worth considering alternatives.

The purpose of reviewing the renewal is to make an informed comparison rather than automatically choosing either option.

Yes, the better starting point is the dedicated Bank Decline Diagnostic.

The goal is to understand why the first application did not work before deciding whether another application makes sense.

Review My Bank Decline
Whatever the mortgage goal

Start with the financial picture.

Buying. Renewing. Refinancing. Investing. Different goals. Same first step:

Understand how the numbers and your income fit together before choosing the mortgage route.

No credit check to start · Initial consultation at no cost · Nothing submitted without your approval