
Start with the goal
Buying a home? Refinancing? Renewing? Purchasing an investment property?
Start with what you are trying to accomplish rather than with a specific bank or mortgage product.
When you own a business, the income on your personal tax return may tell only part of the story.
That can make a standard mortgage application more complicated.
Igor helps Ontario business owners and self-employed borrowers understand how their income may be assessed, what documentation may matter, and which lending routes may fit their circumstances.
No credit check to start · Initial consultation at no cost · Nothing submitted to a lender without your approval
Since 2010
Mortgage professional
Former Scotiabank, CIBC & RBC Mortgage Specialist
FSRA Mortgage Agent Level 1
Licence #M26000762
Serving Ontario
In person, office, phone or Zoom
An employee might earn $150,000 and receive a T4 showing $150,000.
A business owner may generate significant income through a corporation but deliberately pay themselves much less.
That can be good tax planning.
It can also create a disconnect when a mortgage lender tries to determine how much income it can use.
Employee
Earns $150,000 → T4 shows $150,000
Business owner
Significant income through the corporation → pays themselves much less
The goal is not to convince a lender to ignore your tax returns.
The goal is to understand the complete financial picture, document it properly, and identify lenders whose policies may fit the way you actually earn.
You pay yourself through a combination of employment income and shareholder dividends.
Your company generates more than you withdraw personally because capital remains in the business.
Revenue and profit fluctuate between years even though the underlying business remains viable.
Your earnings depend on sales or production rather than a fixed salary.
A significant portion of your earnings comes through ongoing professional or commercial contracts.
Your personal and business income are closely connected, with eligible business expenses reducing taxable income.
You may have business income alongside employment, rental, investment, partnership or other income.
If your income does not fit neatly into one box, that does not automatically mean the mortgage cannot work.
It means the file needs to be understood before assumptions are made.
There is no single universal method every lender uses for every self-employed borrower. The approach depends on the lender, the mortgage program, how the business is structured and the documentation available. A review may involve some combination of:
Your T1 General and Notice of Assessment can establish income reported personally and help identify different sources of income.
If your corporation pays you employment income, the lender may review the salary history and supporting tax documentation.
Dividend income may form part of the assessment where it is properly documented and meets the lender’s criteria.
Depending on the program, lenders may consider reported net business income and, in some cases, eligible adjustments or add-backs.
For incorporated business owners, financial statements may help a lender understand the performance, stability and financial position of the company.
Whether and how corporate income can contribute to qualifying income depends on the lender and program.
How long the business has operated, the borrower’s experience and the stability of earnings can all matter.
Rental income, investments, cash reserves, property equity and other financial resources may also be relevant depending on the application.
The important distinction
A lender is not simply asking, “How much money does this business make?”
It is asking:
“What income can we verify and use under our lending policy?”
That is why preparation matters.
Your accountant may appropriately help you structure your finances in a tax-efficient way.
A mortgage lender has a different job. It needs to establish income it can verify under its lending criteria.
Those two objectives do not always produce the same number.
That is why business owners can find themselves saying:
“My company makes good money. Why does the bank say my income is too low?”
The answer often lies in the difference between:
and
Understanding that distinction early can help you avoid building a home search around a number that a lender may not support.
Do not automatically assume you have to wait.
Two years of business history is common in self-employed mortgage underwriting, but it is not the only situation lenders may consider.
Depending on the lender and program, additional factors can sometimes matter, including:
Whether a mortgage is realistic still depends on the full circumstances.
The useful first step is finding out what can actually be supported rather than assuming either “yes” or “no.”
Mortgage requirements vary by lender and program. Depending on your situation, relevant information may include:
T1 General income tax returns and Notices of Assessment.
Accountant-prepared corporate financial information, which may include compilation, review-engagement or audited statements depending on the circumstances and lender requirements.
Articles of Incorporation, business licence or other evidence of the business structure and operating history.
Where required, business account statements or other information supporting ongoing operations.
Signed contracts may be relevant where they help establish recurring or predictable income.
Documents relating to salary, dividends, commissions, rental income or other income sources may also be required.
You do not need to guess which documents to collect.
Igor will tell you what is relevant to your situation and why it matters.
Important
Do not send SIN numbers, banking passwords, copies of identification, tax returns or confidential financial documents through the public website enquiry form.
Buying a home? Refinancing? Renewing? Purchasing an investment property?
Start with what you are trying to accomplish rather than with a specific bank or mortgage product.
Igor reviews the structure of your income and identifies what requires closer examination.
That may include salary, dividends, business income, corporate information, commissions, contracts or other sources.
Before an application is submitted, determine what may support the file and what could limit it.
Sometimes the issue is income. Sometimes it is debt. Sometimes it is credit, down payment, documentation, the property itself — or a combination.
Collect the information relevant to the lending route being considered.
The objective is a file that is complete, consistent and easy for the lender to understand.
Different lenders have different appetites and policies.
Where appropriate, Igor can review available lending routes that fall within his licence scope and explain their costs and trade-offs.
You review the proposed next step.
Nothing goes to a lender without your approval. Final approval always belongs to the lender.
Business owners sometimes begin their mortgage search by comparing rates.
That makes sense.
But the lowest advertised rate only matters if:
For a self-employed borrower, the better sequence is usually:
Rate matters.
But first the mortgage has to fit.
A self-employed couple came to Igor after being turned down by the banks. They had a clear financing goal, but their income did not fit neatly within the lending criteria they had encountered.
Instead of treating the original decline as the end of the process, Igor reviewed the broader financial picture. That included their business income and the equity they had accumulated in other properties.
The review helped identify another way to structure the financing around their circumstances.
The eventual financing cost was lower than the clients had expected.
Client circumstances have been anonymized to protect privacy. Mortgage options, approval, rates and costs depend on individual circumstances and lender criteria. Past outcomes do not guarantee future results.
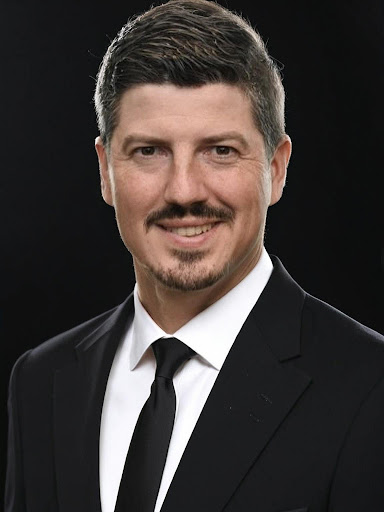
Mortgage Agent Level 1 · Licence #M26000762
Igor Perett began his mortgage career in 2010.
He worked as a Mortgage Specialist with Scotiabank, CIBC and RBC before moving into the broker channel.
That background matters because self-employed mortgage work is rarely about finding one magic lender.
It is about understanding:
Today, Igor is a Mortgage Agent Level 1 with Affinity Mortgage Solutions Inc., Dominion Lending Centres, serving borrowers across Ontario in person, at his office, by phone or on Zoom.
Mortgage Agent Level 1, Licence #M26000762
Affinity Mortgage Solutions Inc., Dominion Lending Centres, Brokerage #13093
Independently owned and operated
Serving clients across Ontario in person wherever suits you, at the office, by phone or on Zoom, in English and Russian.
Self-employment by itself does not prevent someone from qualifying for a mortgage.
The lender will still need to verify the income and assess the complete application under its criteria.
How that is done depends on your business structure, history, documentation and the lender or mortgage program being considered.
Two years of history is commonly used when assessing self-employed income, but some programs may consider borrowers with less than two years in business depending on the circumstances.
Factors such as previous industry experience, predictable income, available reserves and the overall application may matter.
Dividend income may be considered where it is properly documented and fits the lender’s criteria.
How it is treated varies. That is one reason it is useful to review the income structure before selecting the lender.
Corporate financial information can help explain the overall financial position and performance of a business.
Whether retained corporate earnings or other corporate income can contribute to mortgage qualifying income depends on the lender, program, ownership structure and supporting documentation.
It should not be assumed automatically.
Possibly.
Low personal taxable income can make qualification more complex, but the correct answer depends on how your business operates, how you compensate yourself and which documentation and lender policies apply.
The purpose of the Mortgage Readiness Review is to establish what may realistically be considered before an application is submitted.
Variable income does not automatically prevent qualification.
The lender may examine income history, business performance and supporting documentation to determine what income it is comfortable using.
The method varies by lender and type of income.
Not in every circumstance.
Some mortgage programs allow greater flexibility for recently self-employed borrowers where the broader application supports it.
The correct answer depends on your particular situation.
No.
A credit check is not required to begin the Mortgage Readiness Review.
If reviewing credit becomes necessary later, Igor will explain why before proceeding.
No.
Speaking with Igor about a mortgage does not require changing your business banking relationship.
Working with Igor costs you nothing: no charge for the consultation and no fee for arranging your mortgage.
Igor is paid through his brokerage, which is compensated by the lender when your mortgage funds.
You would still have the usual costs of any mortgage, such as legal and appraisal fees, which go to those professionals, not to Igor.
When private financing is the right fit, Igor has it covered through his partnerships with licensed Mortgage Agent Level 2 and broker partners who specialize in it.
As a Mortgage Agent Level 1, Igor connects you with the right partner, and the private mortgage itself is arranged through them.
A private mortgage comes with its own lender and partner costs, and the partner explains them in writing before you decide.
A business owner should not have to discover a mortgage problem after finding the property.
Start with the financial picture. Understand what may work. Identify what may need attention. Then decide what happens next.
No credit check to start · Initial consultation at no cost · Nothing submitted without your approval